
Money and taxes
HECM for Purchase in Colorado: Reverse Mortgage to Buy
A HECM for Purchase is an FHA reverse mortgage that buys your next home with no monthly mortgage payment.
A live person answers. Not a robot, not a phone tree.
A HECM for Purchase is an FHA reverse mortgage that buys your next home. You make a large down payment, the loan covers the rest, and there is no monthly mortgage payment while you live there and keep paying taxes, insurance and HOA dues (CFPB). At least one borrower is 62 or older, and the 2026 limit is $1,249,125 (HUD Mortgagee Letter 2025-22).
Who qualifies?
- At least one borrower is 62 or older (CFPB).
- The home is your principal residence, and you move in within 60 days of closing (HUD Handbook 4000.1).
- You finish a session with a HUD-approved counselor before you apply (CFPB).
- An eligible non-borrowing spouse also moves in within 60 days of closing (HUD Handbook 4000.1).
How much do I put down?
- The down payment depends on the youngest borrower's age, the interest rate and the price (Congressional Research Service).
- An older borrower puts down less.
- {{MIKE}} runs the exact figure on your age and the home you want.
What does the 2026 limit mean on an $800K+ home?
- The HECM maximum claim amount is $1,249,125 for case numbers assigned on or after January 1, 2026 (HUD Mortgagee Letter 2025-22).
- On a $1.5 million home the loan is figured on $1,249,125, so your down payment covers the difference and more.
- On homes near $800K to $1.2M, the limit covers the full price.
What do I still pay every month?
- Property taxes, homeowners insurance and HOA dues (CFPB).
- Missing them puts the loan in default.
- Upkeep on the home stays your job.
- Your lender can require money set aside to pay taxes and insurance (CFPB).
How does a HECM offer look to a seller?
- It is an FHA loan, so the lender orders an FHA appraisal.
- The home must meet FHA property standards, so the appraiser flags repairs.
- Your large down payment shows the seller you are solid.
- We tell the listing agent up front and set dates that give the lender time.
What homes qualify?
- Single-family homes and FHA-approved condos.
- The home must meet FHA property standards and be move-in ready.
- Many luxury condo buildings are not FHA-approved. We check before you write an offer.
Financing by Rate: Mike Oswald, VP of Mortgage Lending, NMLS #261003, (720) 677-5816. Guaranteed Rate, Inc. d/b/a Rate, NMLS #2611. Equal Housing Lender. Licensing: nmlsconsumeraccess.org. You may use any lender; the Kenna Real Estate Group receives nothing for the introduction. Not a commitment to lend; loans are subject to credit approval.
Quick answers
Questions, answered.
Do I make monthly payments on a HECM for Purchase?
No monthly mortgage payment. You keep paying property taxes, insurance and HOA dues (CFPB).
Can I use a HECM for Purchase on a mountain second home?
No. The home must be your principal residence, and you move in within 60 days of closing (HUD Handbook 4000.1).
What is the 2026 HECM limit?
$1,249,125 (HUD Mortgagee Letter 2025-22).
Sources
Where the numbers come from.
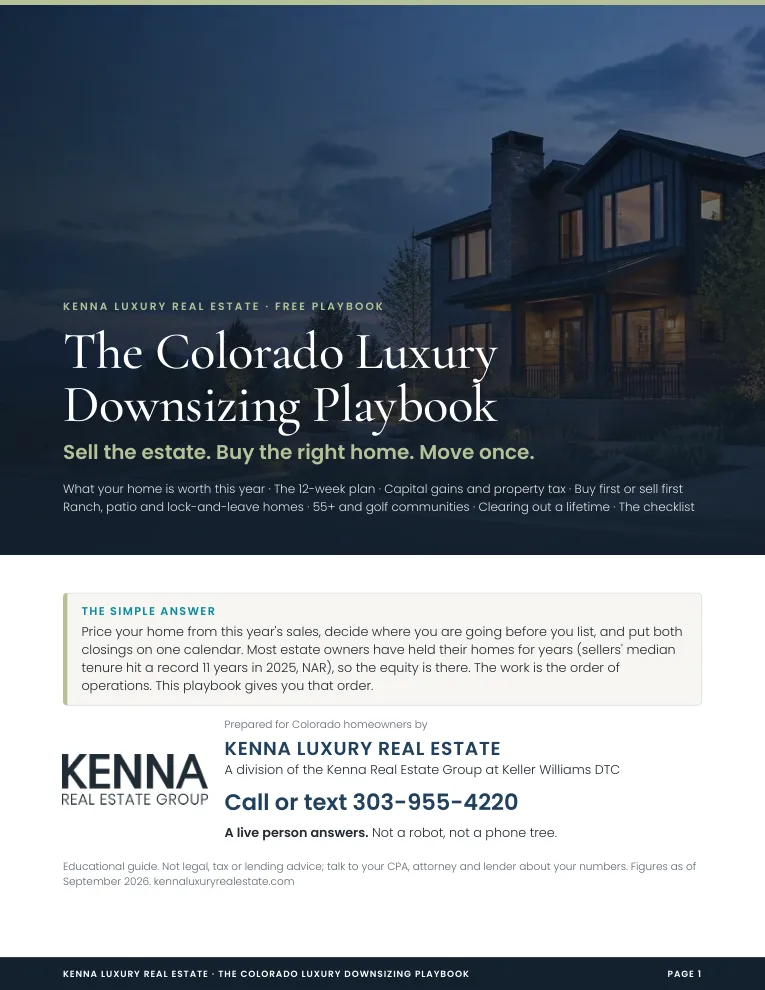
Free playbook
The Colorado Luxury Downsizing Playbook.
Sell the estate, buy the right home, move once. The 12-week plan, the tax and cash questions, the ranch, patio, 55+ and golf communities, and the checklist. 8 pages, free.
A live person answers. Not a robot, not a phone tree.
Private consultation
Ask us about hecm for purchase in colorado.
303-955-4220A live person answers. Not a robot, not a phone tree.
- Private showings on your schedule, including evenings and weekends.
- Off-market homes from the Kenna Real Estate Group's agent network.
- One point of contact from the first showing to the closing table.
Kenna Luxury Real Estate is a division of the Kenna Real Estate Group at Keller Williams DTC (KWDTC).